Tax-deferred
Investment growth
Give your savings time to grow
Investments grow tax-deferred inside the plan. Earnings are generally taxable to the beneficiary when withdrawn, while original contributions are generally not.
Registered Disability Savings Plan
We help families understand DTC eligibility, explore available grants and bonds, and navigate RDSP setup — so you can make an informed decision about your family’s future.
Government of Canada grants & bonds · No cost to find out if you qualify
Lifetime maximums, not a guaranteed payment. Eligibility, income, contributions and available years determine what you receive.
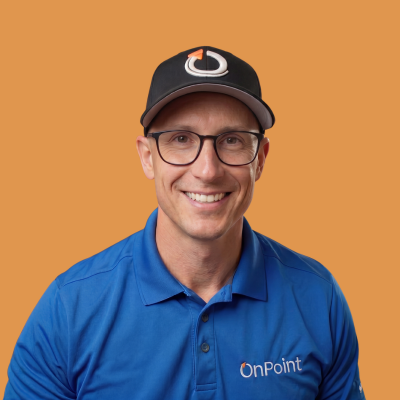
Tyler Hoffman, FMA
Founder · OnPoint Private Wealth Coaching
Financial advising since 2001 · Free, no-obligation RDSP review
Timing matters. Grants and bonds are available through 31 December of the year the beneficiary turns 49. Checking eligibility early can help you make the most of available support and carry-forward room.
What is an RDSP?
A long-term savings plan designed specifically to help Canadians with disabilities and their families save for the future.
Tax-deferred
Investment growth
Investments grow tax-deferred inside the plan. Earnings are generally taxable to the beneficiary when withdrawn, while original contributions are generally not.
$70,000
Lifetime grant maximum
The Canada Disability Savings Grant matches eligible contributions at 100%, 200%, or 300%, up to $3,500 per year, depending on family income and contributions.
$20,000
Lifetime bond maximum
Eligible lower-income beneficiaries can receive up to $1,000 per year from the Canada Disability Savings Bond — with no contribution required.
Lifetime contribution limit: $200,000 — no annual contribution limit. Eligible carry-forward room may increase grant or bond payments in some years.
Eligibility
Even if you don’t meet a single “marked restriction” on its own, you may still qualify if two or more limitations, combined, have an equivalent severe effect.
DTC eligibility is the starting point. RDSP beneficiaries also need a valid SIN, Canadian residency, and must be under 60 when the plan is opened.
Not sure you qualify? CRA bases eligibility on information from your medical practitioner. Different practitioners can certify different impairments; the cumulative-effect category must be certified by a medical doctor or nurse practitioner. A diagnosis alone does not determine eligibility.
Common conditions
These are some conditions that may lead to qualifying limitations. Eligibility depends on their effect on daily life, not the diagnosis alone, and requires medical certification and CRA approval.
Addictions (illegal or prescription meds)
ADHD combined type
ADHD Primarily Hyperactive/Impulsive
ADHD Primarily Inattentive
Alzheimer’s disease
Angina
Anorexia nervosa
Anxiety
Arthritis
Asperger’s syndrome
Ataxia (Cerebellar Dysfunction)
Auditory Processing Disorder (APD)
Autism
Behçet’s disease
Bi-polar disorder (mood disorder)
Borderline personality disorder (BPD)
Bowel Incontinence
Bulimia nervosa
Cerebral Palsy (CP)
Chromosome Abnormality
Chronic fatigue syndrome (CFS)
Chronic pain Disorder
Colitis
Conduct Disorder (CD)
COPD
Coronary artery disease (CAD)
Crohn’s Disease
Dementia
Depression
Diabetes
Difficulty Walking / Dressing
Down Syndrome
Dressing takes longer than on average
Dysgraphia
Dystonia
Fetal alcohol syndrome (FAS)
Fibromyalgia (FM)
Glaucoma
Inflammatory Bowel Disease (IBD)
Irritable Bowel Syndrome (IBS)
Learning Disabilities
Lou Gehrig’s disease
Memory Problems
Mental Illness
Mobility Issues
Multiple Sclerosis
Muscle Dystrophy
Myotonic Myopathy
Obsessive Compulsive Disorder (OCD)
Osteoarthritis
Pancreatitis
Panic Disorder
Paralyzed
Paraplegia
Parkinson’s Disease
Personality disorder
Pervasive developmental disorder (PDD)
Post-Traumatic Stress Disorder (PTSD)
Pterygium
Quadriplegia
Quadriplegic
Rheumatoid Arthritis
Seizure Disorder
Sleep Apnea
Sleep disorder
Speech Disorder
Spinal Cord Trauma
Stroke
Tourette Syndrome
Tuberculosis
Many other conditions may also result in qualifying limitations, including through their cumulative effect.
Personal guidance
An RDSP is one part of a bigger picture. Work with Tyler to understand your options in the context of your family’s needs, rather than looking at an account in isolation.
Understand eligibility, plan-holder requirements and the steps involved in opening a plan.
Explore available government support, contribution timing and eligible carry-forward room.
Consider how an RDSP fits alongside your family’s wider financial needs and long-term goals.
Discuss investment options, risk and time horizons suited to the beneficiary’s circumstances.
Discuss how changing circumstances, contribution decisions and withdrawal rules may affect your plan.
Ask your questions and explore your options before deciding whether to move forward.
How it works
A straightforward process, with support available at every step.
01
The beneficiary needs a valid SIN, DTC eligibility, Canadian residency, and must be under 60 when the plan opens.
02
An adult with legal capacity can hold their own plan. Legal parents or authorised representatives can act in other circumstances; special family-member rules may apply.
03
Choose an issuer and investments suited to the beneficiary. There’s no annual contribution limit, with a $200,000 lifetime maximum.
04
Complete the grant and bond application with your issuer. Eligible support is then paid into the plan, based on income, contributions and available room.
Eligible savings deposits and GICs at CDIC member institutions may be insured within applicable limits. RDSPs are designed for long-term savings; early withdrawals may require repayment of recent grants and bonds.
Frequently asked questions
A Registered Disability Savings Plan is a long-term, tax-deferred savings plan designed to help Canadians with disabilities and their families save for the future, enhanced by government grants and bonds.
GICs, Low Fee ETFs, Segregated portfolio solutions, and savings deposits may be available, depending on your financial institution. Investment values can rise or fall; not all investments are guaranteed.
An adult beneficiary with legal capacity can generally open their own plan. For a minor, a legal parent or other authorised representative can be the holder. For an adult without capacity, an authorised legal representative can act. Ask the issuer which holder rules apply.
Not simply because they are family or friends. A legally authorised representative may open a plan. In certain cases, a qualifying family member (a parent, spouse, common-law partner, or adult sibling) may act for an adult whose contractual capacity is in doubt. This temporary measure is scheduled to end 31 December 2026; confirm current rules with the issuer.
Yes, in some cases, such as legal parents of a minor beneficiary. The issuer can confirm the arrangements permitted for your circumstances.
A person with a valid Social Insurance Number who is eligible for the Disability Tax Credit, is a resident of Canada, and is under 60 when the plan is opened.
Yes, if the beneficiary has reached the age of majority and has the legal capacity to enter into a contract.
No. There is no minimum age to open an RDSP, provided the beneficiary meets the eligibility requirements.
There is no annual contribution limit, but there is a $200,000 lifetime contribution limit per beneficiary. Contributions are not tax-deductible.
Yes, subject to available lifetime room, but doing so may mean missing opportunities to maximise grant matching over several years. Contributions belong to the beneficiary and cannot simply be taken back by the contributor.
Withdrawals can trigger repayment of recent government support. Generally, $3 in grants and bonds is repaid for each $1 withdrawn, up to the applicable assistance holdback amount covering the previous 10 years. Exceptions apply. Grants, bonds and investment earnings are generally taxable to the beneficiary when paid out; original contributions are generally not.
A government match of 100%, 200%, or 300% on eligible contributions, up to $3,500 per year and $70,000 over a lifetime, depending on family net income and contributions. Eligible carry-forward room can allow larger payments in some years.
Up to $1,000 per year and $20,000 over a lifetime for eligible lower-income beneficiaries, with no contribution required. Tax returns must be filed to establish income-based eligibility.
Yes. Eligible grants and bonds can be paid through 31 December of the year the beneficiary turns 49. They are not available for later years, even though a plan may still be opened before age 60.
Get started
Not ready to book? Send Tyler your details and questions to start a conversation. This is an initial review, not a formal DTC eligibility decision.
Prefer to choose a time now?
Book a Free RDSP ReviewYour details are used to respond to your request. They are not sent to Facebook or included in advertising events.
This page is for educational purposes. RDSP eligibility and government grant/bond amounts are determined by the CRA and Employment and Social Development Canada and are subject to change. Maximum support is not guaranteed. Speak with a financial advisor and the CRA for guidance specific to your situation. OnPoint is not a government agency.